How to Review Rising Business Costs Without Cutting Everything
Nov 10, 2026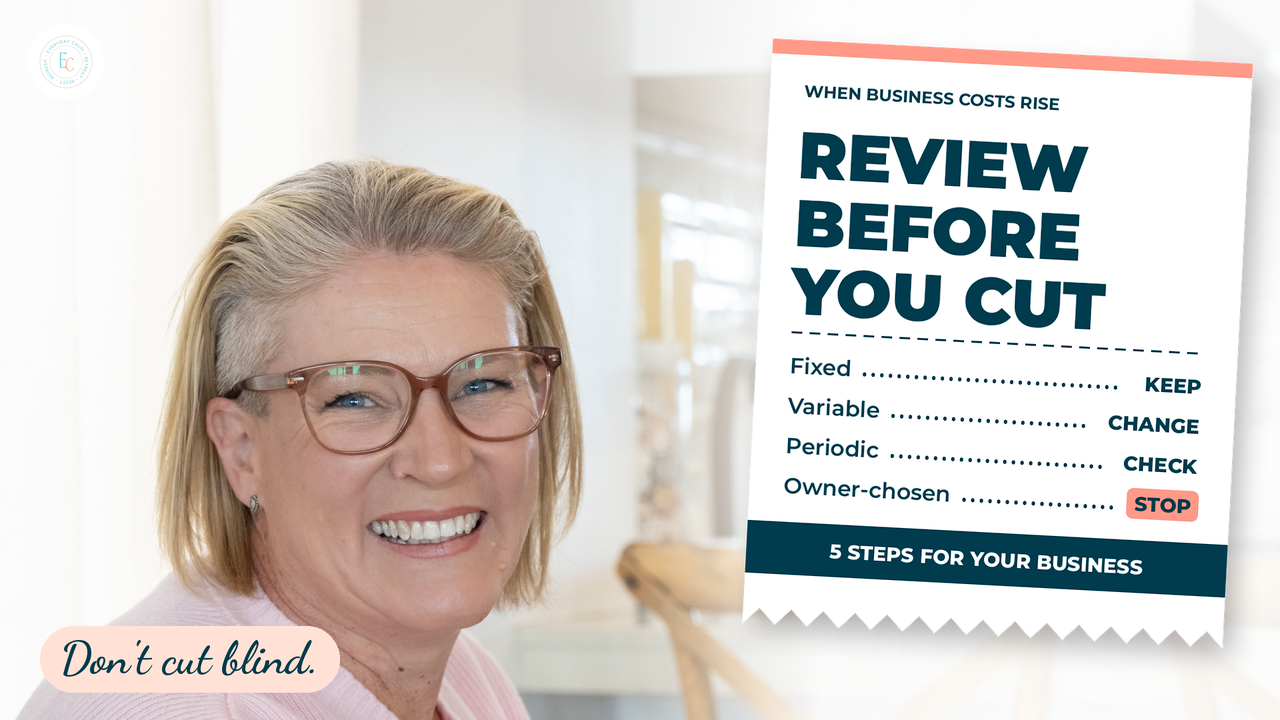
When the Reserve Bank lifted rates again earlier this month, on 3 November, our bank was very quick to pass it on (I got the notification a couple of hours later!).
I'll admit my first reaction wasn't calm - here we go again. It was the same reaction I hear from so many women in business when costs go up. Cut everything. Or work harder and bring in more.
Both feel like action. Though really, neither is a sustainable, long-term plan.
When your business costs rise, the most useful first step isn't cutting everything. It's reviewing. Find out what's changed, sort your costs so you can see them clearly, check what each cost is there to do and look at your margin before you discount or chase more sales. Then choose one cost to look into this week.
That's what this article walks you through.
Why does running a business feel so much more expensive right now?
It isn't in your head. Costs have gone up, and they've been going up for a while.
- The Reserve Bank raised the cash rate to 4.85% on 3 November 2026 - the fifth rise this year and the highest level since 2008.
- The ABS reported that the Consumer Price Index rose 4.3% in the 12 months to September 2026. The CPI measures household prices, not business costs, but as consumers, we feel it in both.
- In its June 2026 survey, the ABS found about half of Australian businesses had higher operating costs. Rising overheads were a reason for 65% of them and staffing costs for 40%.
- AMP Bank Go's Small Business Cost Pressure Index found key small business costs rose 24.6% from March 2020 to March 2026, as reported by AAP. Owners said they were absorbing it through lower margins, longer hours and taking less out of the business themselves.
That last one is the part I want to highlight. When costs rise and nobody's looking closely, the person who usually absorbs them is you.
Why cutting everything usually backfires
A panic cut is a decision made from fear, not from information.
It tends to look like cancelling the marketing that brings clients in, letting the bookkeeper go, or switching off the tool that saves you five hours a week. Meanwhile the subscription you forgot about keeps renewing, because you didn't know it was there.
You're not bad with money. You've been making decisions without being able to see the whole picture.
Cutting blind can leave the business smaller, busier and no less tight. Reviewing first means the cuts you do make are the ones that actually help.
Step 1. Compare what changed, not how it feels
Start with your real numbers instead of the headlines.
Pull up last month's spending and put it next to the same month last year, or three months ago if that's easier. Look for the line items that have moved.
You're looking for answers to three questions:
- Which costs went up?
- By roughly how much?
- Is this a one-off, or will it keep happening?
You don't need a perfect spreadsheet for this. If you use accounting software, your Profit and Loss report already groups your expenses. If you've never read one, start with How to Read a Profit and Loss Statement.
If you'd rather start with one month, my free End-of-Month Money Check-In helps you see what you actually spent.
Interest is worth its own look. If your business has debt like a loan, an overdraft or a credit card, check whether the repayments or the interest charged have changed. Questions about the loan itself should be discussed with your lender, though looking at the interest you're being charged is important.
Step 2. Sort your costs into four types
Once you can see what changed, sort your costs. Each type needs a different kind of decision, so mixing them together is what makes the whole lot feel overwhelming.
Fixed
What it is: Costs you pay whether you see one client or fifty.
Examples: Rent, insurance, software you rely on, loan repayments.
The question to ask: Is this still the right price and the right provider?
Variable
What it is: Costs that move with how much work you do.
Examples: Products used in treatments, payment processing fees, contractor hours.
The question to ask: What does it now cost me to deliver one client, session or job?
Periodic
What it is: Costs that happen every quarter or year, not every month.
Examples: Insurance renewals, registrations, memberships, equipment servicing.
The question to ask: Do I know when it's due, and is money set aside?
Owner-chosen
What it is: Costs you picked that may not be doing their job anymore.
Examples: Subscriptions, memberships, courses and tools you meant to use.
The question to ask: Would I sign up for this again today?
Periodic costs are the ones that tend to ambush business owners. A cost that only shows up once a year is easy to forget, until it has to be paid in the same month as everything else.
Owner-chosen costs are often the easiest place to find room. They're also where it pays to be kind to yourself. Signing up for something hopeful isn't a failure. Keeping it running when it no longer does what it was initially intended to do, that's simply a cost you're allowed to stop paying for.
Step 3. Give every cost a job
Every cost in your business should be doing something for you.
For each cost on your list, finish this sentence: "This cost helps my business ________."
It might help you deliver your service, find new clients, stay compliant, save time or get paid. If you can finish the sentence clearly, the cost has a job. If you can't, that's your first one to question.
Then give each cost one of three labels:
- Keep. It has a clear job and the price still makes sense.
- Change. It has a job, but there may be a cheaper plan, a better provider or a different way to do it.
- Stop. It no longer has a job you need.
This is how you cut with intention instead of cutting everything. You protect the costs that keep the business running and bringing money in, and you make deliberate changes to the rest.
Step 4. Check your margin before you discount or chase more sales
When costs rise, two reactions are really common. Discount to bring more people in, or take on more work at the same price.
Both can make sense. But both have implications, particularly if you don't know where each option will leave you.
Here's a simple example with made-up numbers. Say you charge $150 for a session. Last year the products, fees and other costs of delivering it came to $40, so you kept $110. This year those costs are $55, so you keep $95.
Nothing about your price changed. You're now keeping $15 less from every session.
If you then run a 20% discount, you're charging $120 and keeping $65. You'd need a lot more sessions to end up where you were before your costs rose and you offered the discount.
This isn't a reason to never discount or to raise your prices tomorrow. It's a reason to know your number before you decide. The right pricing decision depends on your business, your clients and your costs.
Earning more is a valid part of the answer too. But more revenue on thin margins can also mean more work, more costs and the same tight bank balance. If your business is profitable and still feels tight, Why Your Business Is Profitable but There Is No Cash in the Bank explains why.
Step 5. Choose one cost to look into this week
Not ten. One.
Pick the cost that moved the most, the periodic cost you're not sure is covered, or the owner-chosen cost you suspect isn't doing its job. Then decide one action.
- Call the provider and ask about a different plan.
- Get one comparison quote.
- Cancel the subscription.
- Write the next renewal date somewhere you'll see it.
- Set aside a small amount each week for the next periodic bill.
One reviewed cost is worth more than a long list of cuts you never get to. When you've done one, the next one feels easier.
A cost review is a habit, not a one-off
Rising costs feel scary when the only time you look at your numbers is when something goes wrong.
Avoidance isn't a discipline problem. It's a visibility problem. When you have a simple rhythm for checking where your money is going, a rate rise or a higher bill becomes something you can see, plan for and respond to. It stops being a shock that sends you into cutting mode.
That rhythm is what I'll help you start building in my free four-day Challenge.
Join the free four-day Making Money Method Challenge
The Making Money Method Challenge runs from 23 to 26 November 2026.
Over four days, we'll look at where your business money is going, what's driving the patterns that keep it feeling tight and one practical habit you can keep using after the Challenge ends. You won't be doing it alone.
Register for the Making Money Method Challenge.
You don't have to cut everything to feel more in control. You need to be able to see what you're working with.
This article provides general educational information only. It doesn't take into account your individual circumstances and isn't personal financial, tax or legal advice. For decisions about loans, debt or pricing in your business, speak with a qualified professional.